Arctos Partners Acquires 10% Stake in Atlanta Falcons at $10.6B Valuation While Keeping Control in Family Hands
Arctos Partners has agreed to acquire 10% of the Atlanta Falcons at a reported $10.6 billion enterprise valuation, and the buyer gets no vote on how the team runs. CNBC first reported the agreement in August, and NFL owners are expected to consider it at their October 20-21 meeting in New York. If you have ever wanted a slice of an NFL team without any say over who plays quarterback, Arctos is showing how that arrangement works at the top of the market.
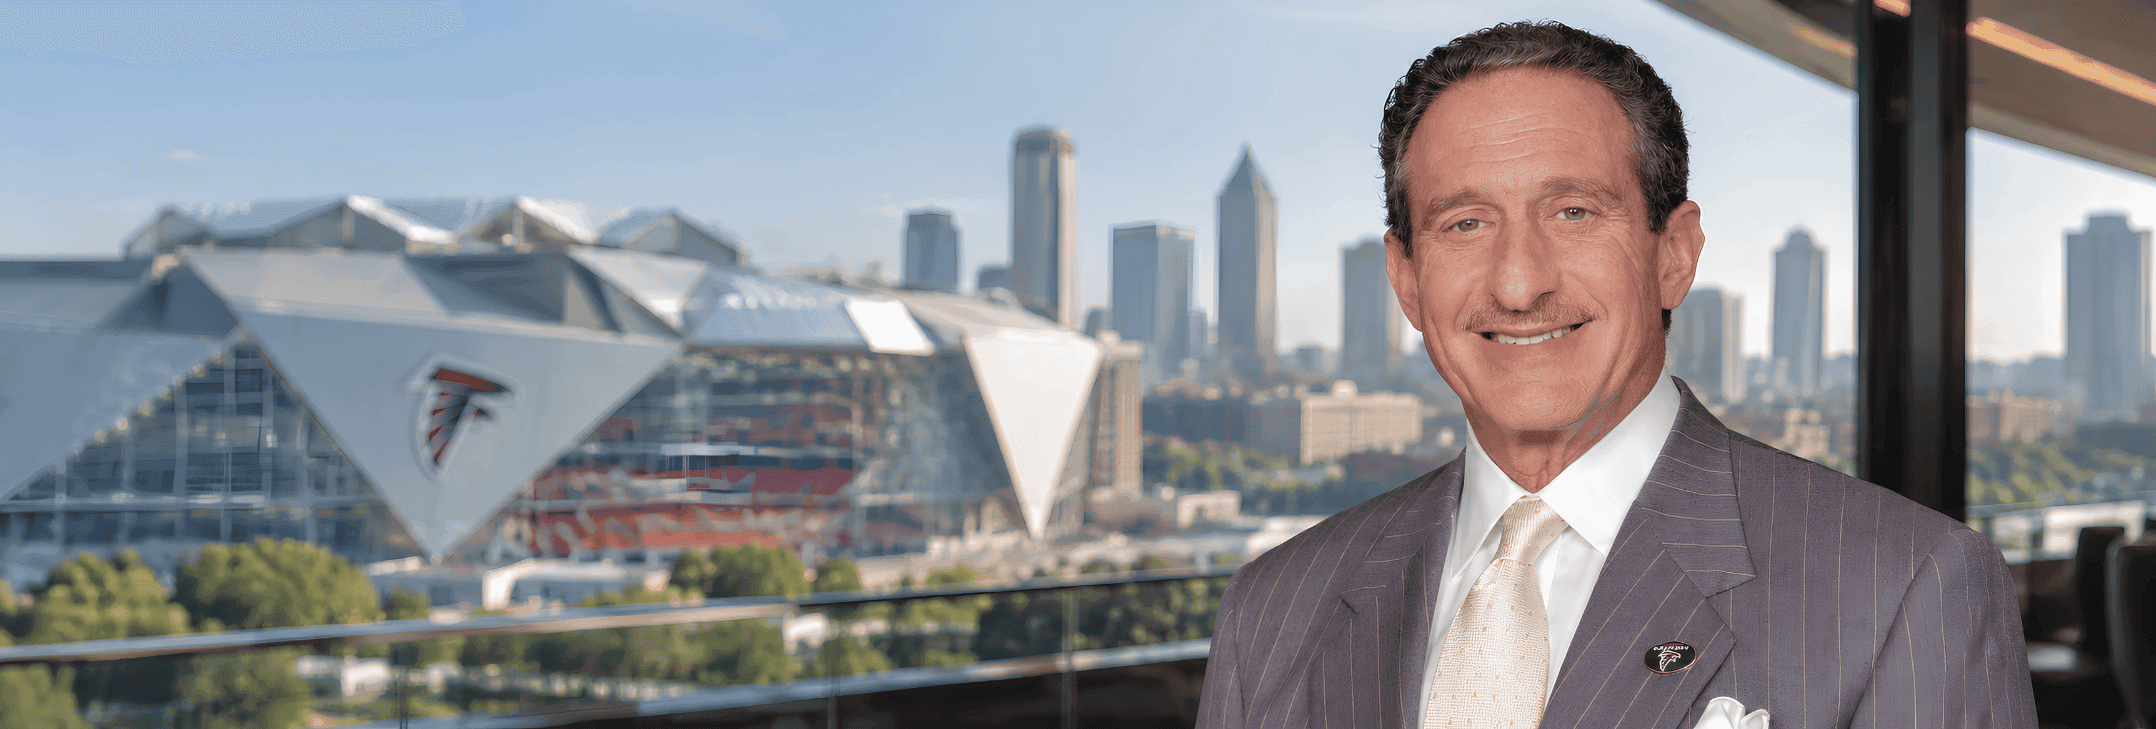
Arthur Blank, the Home Depot cofounder, bought the Falcons for $545 million in 2002, so the reported valuation stands at more than 19 times his purchase price. He owned just under 73% when the agreement emerged and would retain 63% after approval, according to Sports Business Journal. For Blank, the proposed deal creates a way to raise cash for his family’s charitable ambitions beyond football while his family keeps its grip on the franchise.
Blank Can Raise Cash Without Handing Over the Keys
Per Sportico, the transaction unfolds in two stages. Arctos would initially acquire 7.5% at a valuation just above $10 billion, then buy the remaining 2.5% roughly 18 months later at an enterprise value around $11 billion. CNBC reports $10.6 billion for the overall arrangement. Neither report explains the reason for splitting the purchase, and the actual cash payment remains undisclosed. Enterprise value includes debt, so multiplying the headline figure by 10% cannot establish the cheque the sellers receive.
The same care applies to the apparent jump from CBNC’s $8 billion estimate in September 2025. The deal’s reported valuation sits about 32.5% above that estimate, but comparing an estimate with a negotiated transaction cannot prove the franchise’s price rose by that amount. Likewise, the comparison with Blank’s $545 million purchase excludes subsequent investment and distributions. Even with those limits, the figures show just how much more valuable an NFL ownership stake has become during his tenure.
Meanwhile, Atlanta’s business gives investors something to work with despite eight consecutive seasons without a playoff appearance. Sportico estimates last season’s revenue at $800 million and puts annual sponsorship revenue above $100 million.
“Despite average performance on the field the last several years, our business has been really strong,” Falcons CEO Greg Beadles told CNBC. The investment case can survive a disappointing season.
Initially, CNBC could not establish whether Blank, his limited partners, or both would sell. Since then, Sports Business Journal reported on September 10 that Blank would hold 63% after approval. He expected a reduction in the value of his shares by supplying the stake (the detailed seller breakdown remains unpublished). The distinction decides who gets the money: selling Blank’s shares gives him cash; selling a limited partner’s shares gives that investor liquidity. His reported remaining holding also leaves him comfortably in control.
Arctos Buys In Under Strict Rules
Keeping control is central to the rules NFL owners approved in August 2024. Their 31-1 vote opened the league to approved private equity investors, with a combined 10% ceiling per team, even when several funds invest. Those holdings carry no voting rights and an initial minimum six-year hold, so an owner gains a patient financial partner without surrendering decisions about the franchise. Meanwhile, the controlling owner must retain at least 30%, which leaves Blank room to sell his shares while preserving that position.
Commissioner Roger Goodell explained the reasoning after the 2024 vote, “We're doing it with a cap of 10%, so it's a much less significant position. But I think it's an appropriate thing to give teams that liquidity and to reinvest in the game and to their teams.” The ceiling remains intact. And owners have no immediate appetite to raise it and are not expected to discuss an increase in October, per Front Office Sports September 24 reports. (The league declined to comment).
Arctos therefore has to build its portfolio within those limits. Atlanta would join the Bills, Chargers and Browns as its fourth NFL investment, leaving two places under the six-team limit for a single fund. Its financial backing has changed, though: KKR completed its acquisition in May, following an agreement worth $1.4 billion initially, plus up to $550 million in additional equity tied to performance and KKR’s share price. Arctos managed about $16 billion at closing, but its new parent does not remove the NFL’s restrictions.
Blank Has Been Planning For This for Years
For Blank, selling economic interests while keeping control has a much longer history. IN July 2009, he agreed to bring in four minority investors and linked the decision to charitable and estate planning. “I have no intention of selling the club or even a controlling interest in the club,” he said.
Private equity entered the NFL 15 years later, giving owners another route to a result Blank had been pursuing with individual investors. The buyer changes, but his ability to retain the team continues.
He returned to the market in 2019, selling 10% for about $300 million ot three individual minority investors at a valuation he put near $3 billion. “We got a very acceptable valuation based on the trends in the league, sales of teams, sales of ownership, and what have you. There is no discount for being a minority owner,” he told Sports Business Daily. His assessment describes that transaction, but it also shows why an owner might welcome another buyer willing to accept limited power.
Now in his 80s, Blank gives a concrete explanation for considering further sales. In the September interview with Sports Business Journal, he said funding decisions would depend on cash flows, investments, and his foundation needs. “We want to continue to fund the foundation at high levels,” he said, adding that his children share that ambition. He also described viable alternatives to Arctos among approved buyers. A valuable team can support those ambitions, provided he can turn some shares into spendable money.
Family ownership makes that flexibility important. SaportaReports described the Smith family’s 2002 sale as a way to meet estate taxes and distribute proceeds among relatives. Blank’s circumstances differ, and his public comments establish charitable funding as a current concern. In 2024, his executive Brett Jewkes told the publication that Blank intends the Falcons to remain in family hands. A passive investor fits that aim by releasing money while leaving the family free to plan the franchise’s future.
Seattle Offers a Different Benchmark
Seattle shows how another family’s plans can lead to a different outcome. The Khosla group’s record $9.612 billion purchase won unanimous NFL approval on August 26, and the sale closed on September 3. Paul Allen’s estate followed his direction to sell his holdings and support philanthropy. Seattle transferred control to a new ownership group, while Atlanta’s proposed buyer accepts a passive interest. Those differences limit any comparison between Seattle’s sale price and Atlanta’s $10.6 billion enterprise valuation.
The October vote could nevertheless give the other 31 owners an important reference when considering their minority sales. Approval would endorse a transaction at a reported valuation above $10 billion while Blank retains control. For owners weighing cash needs and a desire to keep their teams, Atlanta would provide another negotiated example to take into the room.